It’s the open enrollment period for the Health Insurance Marketplace, Medicare, Medicaid and employer healthcare plans across the country. If you have lupus, here is what to look for in your healthcare plan.
Understanding Your Insurance Costs:
Insurance Premium: The amount you pay each month to maintain your health insurance coverage, regardless of whether you use medical services. Plans with lower monthly premiums often have higher deductibles and out-of-pocket costs, while plans with higher premiums may offer lower costs when you receive care.
Deductible: The amount you pay for covered healthcare services before your insurance begins sharing the cost of certain services. For example, if your deductible is $2,000, you may need to pay $2,000 toward covered medical expenses before your insurance starts paying its share. Some services, such as preventive care or certain prescriptions, may be covered before you meet your deductible.
Out-of-Pocket Maximum: The most you will have to pay during your plan year for covered, in-network healthcare services, including applicable deductibles, copays and coinsurance. Once you reach your indicated out-of-pocket limit, your insurance pays 100% of covered, in-network costs for the remainder of the plan year. Monthly premiums, noncovered services and most out-of-network expenses do not count toward this maximum.
Tip for lupus patients:
If you anticipate frequent specialist visits, expensive medications, infusions or ongoing testing, compare plans based on your total estimated annual costs, not just monthly premiums.
A higher-premium plan with a lower deductible and out-of-pocket maximum could save you thousands of dollars over the course of a year. Out-of-pocket maximums especially help those on biologics such as Benlysta, Saphnelo or IVIG.
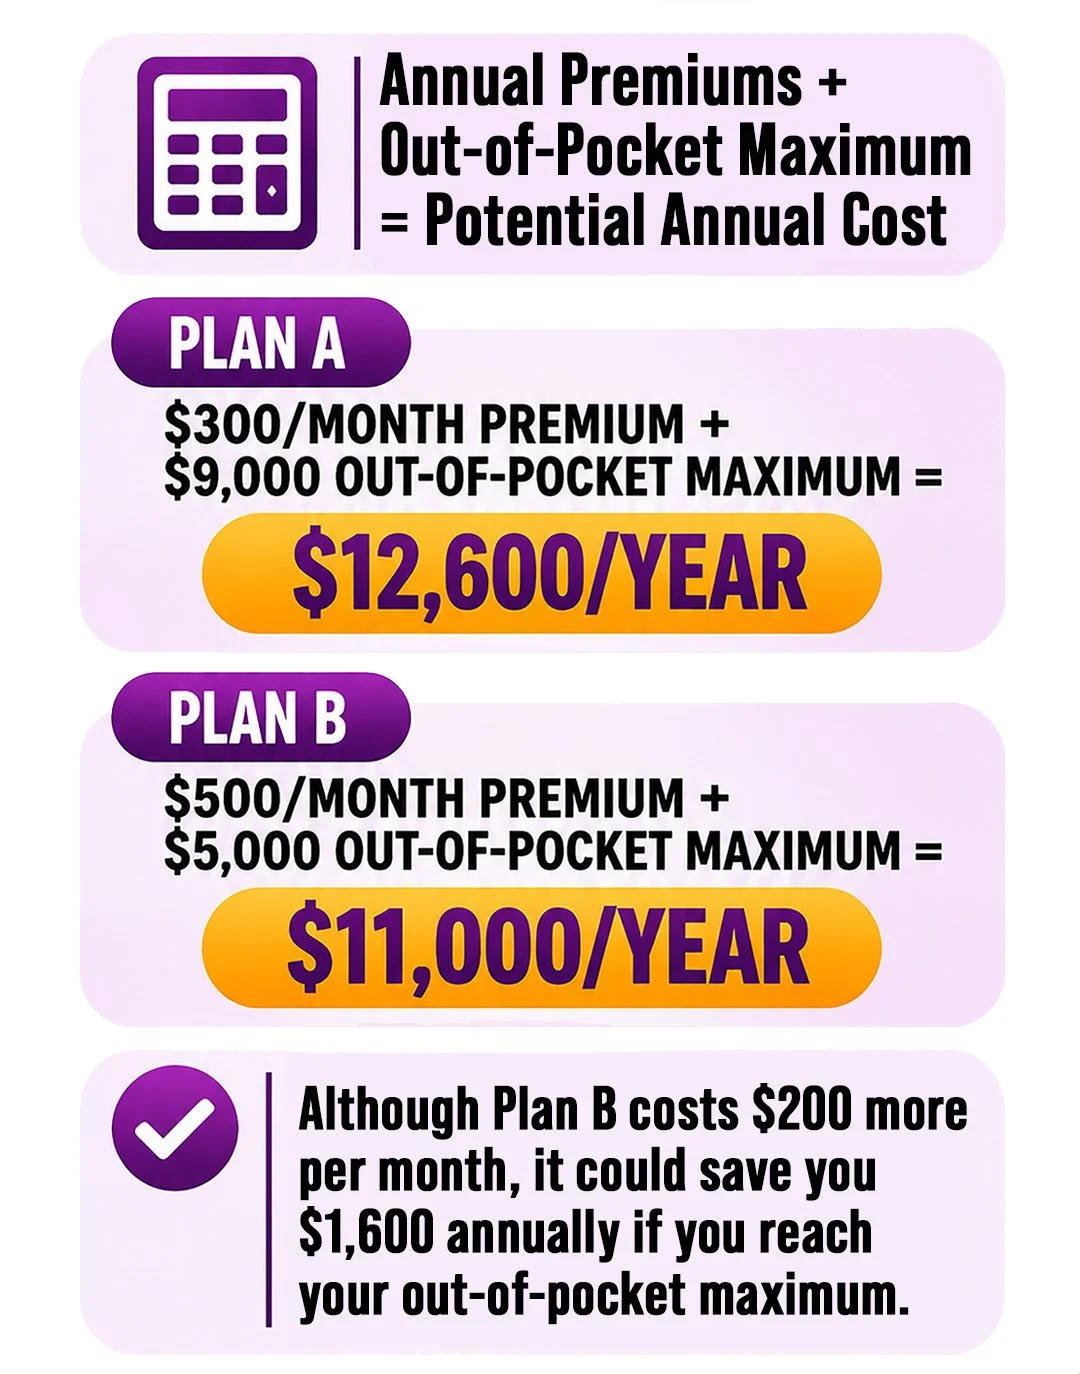
Annual Premiums + Out-of-Pocket Maximum = Potential Annual Cost
For example:
Plan A: $300/month premium + $9,000 out-of-pocket maximum = $12,600/year
Plan B: $500/month premium + $5,000 out-of-pocket maximum = $11,000/year
Although Plan B costs $200 more per month than Plan A, it could save you $1,600 annually once you reach your out-of-pocket maximum.
The cheapest monthly plan isn't always the most affordable plan for someone living with lupus.
Check Medication Coverage:
Make sure your prescriptions, biologics and infusions are covered under the plan’s drug formulary or medical benefits. Check medication tiers, copays and coinsurance, especially for expensive specialty medications. Watch for prior authorization requirements, step therapy (requiring you to try less expensive medications first) and restrictions on where prescriptions can be filled or infusions administered.
Verify Your Doctors:
Confirm your rheumatologist, primary care physician, specialists and preferred hospitals are in-network. Out-of-network care can be significantly more expensive or may not be covered at all. Check whether specialist visits require referrals and whether your preferred lupus treatment centers accept the plan.
Watch for Copay Accumulators:
Some insurance plans use copay accumulator programs that prevent manufacturer copay assistance from counting toward your deductible or out-of-pocket maximum. This means you could exhaust your financial assistance and still owe thousands of dollars toward your healthcare costs. Ask your insurer whether it uses copay accumulators or maximizers and how manufacturer assistance is applied.
Review Medical Benefits:
Lupus often requires ongoing monitoring and specialized care. Check coverage for routine blood work, kidney function tests, imaging, specialist appointments, infusions, emergency care and hospitalizations. Pay attention to copays, coinsurance, deductible requirements and whether certain services require prior authorization.
Know Your Rights:
Insurance companies may deny coverage for medications, procedures or treatments, but doctors and patients generally have the right to appeal these decisions. You are your own best advocate, so don't be afraid to speak up, challenge denials and keep fighting for the care you need.
Expert Help:
Receive free or professional assistance choosing the right health insurance plan for your needs.
Marketplace / ACA: Free, unbiased help from certified Navigators through HealthCare.gov, or assistance from licensed insurance agents and brokers.
Medicare: Free counseling through SHIP (877-839-2675) or assistance from Medicare.gov (800-633-4227).
Medicaid: Contact Michigan Enrolls (800-975-7630) or visit MI Bridges.
Employer-Sponsored Insurance: Contact your HR or Benefits Department or your insurance provider directly.
These resources can help you compare coverage, understand costs and find a plan that meets your healthcare needs.